Sandra Meranda

  • Home
  • About Sandra
    • Information for Buyers and Sellers
  • Blog
  • Contact Sandra

July 29, 2011 by changescapeweb Leave a Comment

4 Steps to Minimize the Risk of Owning a Home

Many new or first-time home buyers in St. Charles and St. Louis MO are concerned about the risks of owning a home.  Here’s a great article written by Tara-Nicholle Nelson, a Broker in San Francisco, CA on 4 steps to minimize the risk of owning a home.
4-Steps-to-minimize-the-risks-of-home-ownership-300x89

Not so long ago, in a not-so-distant land, owning a home was thought of as the safest “investment” around. Fast forward to the present day, and home ownership seems super scary to many people who can afford homes, and would like to own them, but are paralyzed by the fear of buying a lemon, or having a mortgage catastrophe.

Here are 4 simple steps to minimize the risk that you’ll become the main character in a homeownership horror story.

1.  Stick with a fixed-rate mortgage.  Recent data shows that adjustable rate mortgages, or ARMs, are increasingly popular, rising from 9 percent of the mortgage market in the fourth quarter of 2010 to 12 percent in the first quarter of this year.  This might seem crazy to some, but in financially aggressive crowds, the lure of low, 3 percent(ish) interest rates on ARMs is enough to overcome any qualms.  As well, today’s ARMs tend to have lower lifetime interest rate caps and require payment of principal, so they don’t adjust as violently as the subprime interest-only and option ARMs that contributed to the foreclosure crisis.

If the thought of your mortgage payment changing over time gives you the shakes, you don’t want to live in a state of interest rate obsession for the next few decades, or you simply crave the simplicity and predictability of knowing what your housing payment will be for the next 15, 20 or 30 years, then stick to a fixed-rate mortgage.  The rates are higher, but with a fixed-rate loan, the risk of scary payment changes are not only lower, they are non-existent.

2.  Put – and keep – a home warranty in place.  One of the most frightening things about going from renter to homeowner is the prospect of being solely responsible for the care and feeding of your home and all its systems and appliances. Responsibility for both the costs and the actual logistics of repairing things like a leaky roof, a broken hot water heater or a haywire electrical fixture looms large in the minds of first-time buyers, in particular.

A home warranty plan kicks in when escrow closes, and depending on the coverage you select, will cover your home against the breakdown of major systems and even some appliances, like furnaces and water heaters.  In some cases, you can even upgrade the coverage to protect against roof leaks and some plumbing issues. When a covered item breaks down, just remember to call the home warranty company first – for the cost of a service call you can get the item repaired or even replaced, if necessary.  I remember the home warranty company replacing a $900 water heater in my first home; what a godsend!

Talk with your agent – you might even be able to negotiate for the seller to pay for the first year’s cost of the warranty.  Just remember to renew it when it expires every year, to keep a cap on your risk of unexpected repair costs for the duration of your tenure as a homeowner.

3.  Get repair bids and estimates, not just inspections.  After you find the home of your dreams (or the home of your budget!) and get into contract, you’ll have a contingency or objection period ranging from 7 to 17 days during which you can obtain all the inspections you want.  Most buyers start out with a general property inspection, a pest inspection and a roof inspection, then get more specialized inspections if the property calls from it.  Pest and roof inspectors will generally provide an inspection report AND a repair bid for any work they find needs to be done.

But the overall home inspection could very well list a dozen needed repairs, upgrades and maintenance items, without providing any information about how much those repairs will cost.  If your inspection report surfaces work you’ll need to have done to fix things (or avoid bigger fixes down the road), work with your agent to schedule actual repair contractors to come in and give you bids on the work before your contingency or inspection period expires.  That will position you to negotiate around repair costs with the seller, or to know what you’re getting yourself into, cost-wise, if you take the property as-is.

4.  Buy on the 10-year plan.  Warren Buffett once famously advised stock investors to “only buy something that you’d be perfectly happy to hold if the market shut down for 10 years.”  The same advice is good for buying a home in today’s real estate market.  Take on a mortgage you know you can sustain, buy at a price you can comfortably afford and avoid having to sell because you need to move for some urgent reason, or because the home no longer meets your needs.

You can take this last step to hedge against losing money on your home by planning your space, career and lifestyle needs out 5, 7, even 10 years in the future – everything from how many bedrooms and garage spaces you’ll need to where you’ll want to be located, geographically – and selecting a home that will meet those needs for that foreseeable future. As a general rule of thumb, the harder hit the area was in the recession, the longer you should plan to hold it.

A top real estate agent can help you make an informed decision about whether it is the right time to buy, and the best ways to minimize the risks of home ownership in St. Charles County and St. Louis County.  My team specializes in St. Charles and St. Louis County.  If you are considering buying a home, please contact Sandra Meranda and I’ll get you moving!
Filed Under: Buying a Home, Home Ownership

July 1, 2011 by changescapeweb Leave a Comment

St. Charles and St. Louis County Real Estate – Buy Now or Wait?

There are plenty of homes for sale in St. Charles County and St. Louis County.  There are some great deals, but will they get better?  Just because a home drops in price doesn’t necessarily mean that the house will cost less.

Interest rates are key in determining the total cost of the house, and as a result need to be factored in as a major consideration in whether to buy a St. Charles County or St. Louis County home now — or wait.  The following article does a great job of explaining this!

Buy Now or Wait?

by Pat Zaby May 23, 2011 15:59 PM

Uncertainty as to whether prices will continue to fall has to be one of the most common causes of buyer procrastination.  Paying too much wouldn’t be a smart thing but price isn’t the only factor to consider.  Interest rates have as much effect on housing costs as price.

A small increase in mortgage interest rates can offset a significant drop in home prices.  If the price of the home were to come down by 5% but the interest rates were to go up by .5%, the payments might be close to the same.

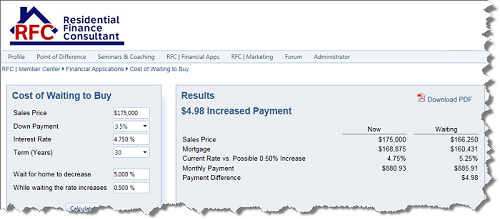
In the example below, if the price of $175,000 home went down 5% but the interest rate went from 4.75% to 5.25%, the payments would actually be $4.98 more at the cheaper price.  If while the buyer was waiting for the home to decrease 5% and the interest rate increased by 1%, the payments would actually go up by $55.30.

Buy-now-or-sell-example

Then, of course, there is always the possibility that the price of the home doesn’t go down but the rate does go up by 1%.  The payments would be $104.58 more per month, each and every month for as long as you have the mortgage on the home.

A Residential Finance Consultant can provide solid information that will help you make better buying decisions.  A home is a place to feel safe and secure, to raise your family, share with your friends and an investment.  It’s an investment in your marriage, your family and your future.  You owe it to yourself to check out the real numbers in your market because every market is different.

A top real estate agent  and mortgage banker can help you make an informed decision about whether it is the right time to buy in St. Charles County and St. Louis County.  My team specializes in St. Charles and St. Louis County.  If you are considering buying a home, please contact Sandra Meranda and I’ll get you moving!
Filed Under: Buying a Home

June 28, 2011 by changescapeweb Leave a Comment

St. Louis Remodeling Cost vs. Value

People in St. Charles and St. Louis are always asking if remodeling adds value to their home before they want to sell it.  Remodeling projects might make it easier to sell a home, but what percentage of the cost can be recouped as a part of the sale?

I came across this article which provides data for the St. Louis and St. Charles area for 35 remodeling projects which includes a comparison of:

  • the cost of the job
  • the resale value
  • percentage of cost recouped
  • city to regional and national comparison

Projects were broken out by midrange homes and upscale homes.

Only one project recouped more than 100% of the cost, and this was at the National level for a steel entry door replacement.

The St. Louis area trailed behind the national average in regard to the percentage of costs recouped for remodeling projects.

Most projects recouped between 50% and 65% of their costs, with the steel entry door and new garage door replacements recouping the highest percentages.

See the full results form the 2010-2011 Remodeling Cost vs. Value report  for the St. Louis area.

It’s important to work with a top real estate agent with experience in the St. Charles and St. Louis metro areas to determine if that home remodeling project really will pay for itself or recoup most of the cost.  A top real estate agent can help home sellers understand which home remodeling projects will help with the sale of the home and allow the seller to recoup costs.

If you are thinking about buying or sell in home in St. Charles or St. Louis counties, please contact Sandra Meranda and I’ll get you moving!

Filed Under: Home Remodeling, Home Selling

May 26, 2011 by changescapeweb Leave a Comment

5 Things Home Buyers Do That Turn Sellers Off (and Kill Deals)

I wanted to share this article – it has some great tips about how home buyers can avoid turning off the home seller, and potentially keeping you from getting the home you want at the best price and terms.

On today’s market, every savvy seller wants to know what turns buyers off, so they can get their homes sold as quickly as possible, for as much as possible.  But buyers, take note – there is a minefield of seller turn-offs you can trigger that hold the potential to keep you from getting the home you want at the best price and terms, or to unnecessarily complicate dealings with your home’s seller.

Lest you think all of today’s sellers are under the gun and will just put up with whatever behavior buyers dish out, be aware that there are still many multiple offer situations in which buyers have to compete with each other to get a home – buyers who trigger these turnoffs tend to lose in those scenarios.  Also, avoiding these seller turnoffs can create a transactional environment of cooperation and avoid things turning adversarial.  That, in turn, can empower you to score a better price, get extra items you want thrown into the deal, and even negotiate more flexibility around your escrow and move-in timelines – all perks that can make your life easier and your budget go further.

For sellers, these turnoffs pose the potential of irritating you out of an otherwise good deal – maybe even the only deal you have!

Here’s a few of the most common buyer-perpetuated seller turnoffs, with tips for sellers on how to keep an emotional (and economic) even keel, even if your home’s buyer makes some of these waves:

1. Trash-talking. Trash-talkers are the home buyers who think they’re going to negotiate the list price down by slamming the house, telling the sellers how little it is really worth, how the house across the street sold for nothing, why the school on the corner should make them desperate to give the place away, etc. This strategy never works; in fact, when you attack a seller and their home, you only cause them to be defensive, and think up all the reasons that (a) their home is not what you say it is, and (b) they shouldn’t sell their home to you!

Sometimes this happens with buyers who actually love a house and just walk around it fantasizing about all the ways they would customize it to their tastes while a seller is there.  Sellers: avoid being at home while your home is being shown.  Buyers: save your commentary for your agent; if you do encounter the seller in person keep your conversation respectful and avoid critiquing the house or the list price.

2. Being unqualified for mortgage financing. When a seller signs a buyer’s offer, most often the seller agrees to effectively pull the home off the market, forgoing other buyers who might be interested.  As such, the only thing worse than getting no offers on your home is getting an offer, getting into contract, then having the whole thing fall apart when the buyer’s loan falls through – especially if that could have been predicted or avoided up front.

Sellers: Work with your agent to vet your home’s buyers’ qualifications, including their loan approval, down payment and earnest money deposit – before you sign a contract.  It’s not overkill for your agent to call the buyers’ mortgage pro before you sign the contract and get a level of comfort for how robust their qualifications are.  Buyers:  Get pre-approved.  Seriously.  And make sure that you don’t buy a car, quit your job, deposit lottery winnings or do any other financial twitchery between the time you get loan approval and the time you close escrow on your home.

3. Making unjustified lowball offers. No one likes to feel like they are being taken advantage of.  And sellers generally know the ballpark amount that their home is worth, as well as what they need to sell it for to get their mortgage paid off.  Yes – the price you pay for a home should be driven by its fair market value, rather than the seller’s financial needs, and deals are more available in a market like the current one, in which supply so vastly outpaces demand. But just throwing uber-lowball offers out at sellers hoping one will hit the spot is not generally a successful strategy, especially if you really, really want a given property.

Sellers:  Don’t get overly emotional about receiving a lowball offer; counter at the price you and your agent decide makes sense based on the total circumstances, including your motivation level, recent comps and the interest/activity level your listing is receiving. Buyers:  Work through the similar, nearby homes that have recently sold (a/k/a comparables) before you make an offer to factor the home’s fair market value into your offer price – also factor in how much you want the place, too.  Don’t be amazed if you make an offer far below asking, and don’t get a response.

4. Renegotiating mid-stream. Sellers plan their finances, moves and  – to some extent – their lives around the purchase price a buyer agrees to pay for their home.  If you get into contract to buy a home, find out during inspections that costly repairs need to be made, then propose a lower sale price, repair credit or even actual repairs to the seller, that’s sensible and fair.  But if you were aware that the property needed a lot of work before you made an offer on it, then you come back asking for beaucoup bucks’ worth of credit or price reductions midstream, expect the seller to cry foul.  And holding the seller up two weeks into the transaction because you caught a case of buyer’s remorse? Not cool, and not likely to foster the spirit of cooperation you may need to get your deal closed.

Sellers: avoid mid-stream price renegotiations by having a full set of inspection reports and repair bids at hand when you list your home. Buyers: try to avoid renegotiating the entire deal unless you get some major surprises at your inspections or inflating small repairs to try to justify a major price cut.

5. Misleading or setting the seller up.  Remember when we talked about buyer turn-offs?  Being misled by listing photos or very fluffy property descriptions was high on the list.  The same goes for sellers.Offering way over asking with the plan to hammer the seller for a reduction when the house doesn’t appraise at the purchase price?  #LAME  Making an as-is offer planning the whole time to come back and ask for every penny ante repair called out by the inspectors?  Lame squared.

Sellers:  If you get multiple offers and are tempted to take a sky-high one or one that claims to be all cash, consider requesting proof that the buyer has sufficient funds to make up the difference between what you think the home will appraise for and the actual sale price, and statements showing the cash truly exists.  Buyers: Don’t be lame. I’m not saying you have to tell the seller exactly what your top dollar is, but making offers with terms designed to intentionally mislead is really, really bad form – and can result in losing the home entirely if and when your bluff gets called.

This article on Home Seller turn-offs was originally posted on Trulia.com

Sandra-Meranda-Sold-FastSpring has sprung in St. Charles and St. Louis!  This is the time of year for buying and selling real estate.  There are large numbers of homes at below-market prices & the move-up market has been energized for the Spring.  Interest rates are hovering around 5% & home sale numbers have been increasing every month, it is a great time to list your home also.  Contact me for details today!
Filed Under: Home Selling

May 20, 2011 by changescapeweb Leave a Comment

4 Signals It Might be Time to Buy (vs. Rent) Your Home

This is a great article to help people in St. Charles and St. Louis determine if they should buy a home, or rent.

To rent or to buy:  what used to be a given – that you would buy a home as soon as you could afford to – has become an agonizing conundrum for many a would-be homebuyer, in the face of the housing market’s big bust and super-slow recovery.  Low prices seem to create a wide-open window of opportunity, but they also create the concern that prices will keep falling after closing.  And that Catch-22 has hundreds of thousands of buyers-to-be stuck on the fence.

Fortunately, there are handful of life, mortgage and local market signals which indicate that the time *might* be right to hop – scratch that – leap off the fence and into homeownership:

Mortgage rates are going up.  Home prices have been low for the last several years, and in fact are currently looking like they’re heading back down to the same levels they were at the depths of the real estate recession. During this same time frame, interest rates have also been low – this one-two punch has created record-high affordability for the last four years running, causing buyers to believe that this window of opportunity won’t be closing anytime soon.

While prices don’t look like they’ll be skyrocketing anytime soon, interest rates are another story. Rates have been on a rollercoaster over the past few months, and with inflation and Fed rates set to spike later this year, today’s low interest rates might be as good as they’re going to get for a long time to come.  And I mean a very long time – in the next few years, governmental intervention in the mortgage markets is likely to wind down, and that means higher mortgage interest rates are not only inevitable, they’ll probably be here for a long, long time.

Mortgage rates on the rise are one signal that now might be the peak of home affordability, and the peak of the opportunity to buy.

Rents are going up.  Rental rates in many areas are also on the rise – in fact, the foreclosure crisis has acted created additional demand on many markets’ rental housing inventory in several different ways. First, former homeowners who lost homes to foreclosure now need to rent; as well, buyers in foreclosure hot spots have been hesitant to buy, many electing to stay renters far beyond when they would have otherwise. On top of all that, super-tight lending guidelines have stopped even some who would like to buy homes from doing so.  As a result, rental homes are in high demand – and rents are rising.

Rising rents at a time when the prices of homes for sale are low and, in some places, falling?  One more signal that now might just be the time to buy. (Of course, where foreclosures are high, the chances of continued depreciation are, too – to offset this risk, have a long-term plan, to minimize the possibility that you’ll owe more than your home is worth when you need to sell.  Read on for more on how to plan for the long term and minimize your homebuying risk.)

Your income and career are stable for the foreseeable future.  The smartest homebuyers look to their lives, not just the market, for signals about when the time is right to buy. Homebuying is a long, long-term endeavor these days. The goal is to be able to commit to staying in the same place, geographically-speaking, for 7 to 10 years before you buy (more in a foreclosure-riddled market, less in an area that has been more recession-resistant). Most lenders will require that you’ve been at your job – or in the same general field of work – for at least two years before you buy. But that’s the bare minimum – beyond that, you don’t want to be barely beginning a career in which you think you may need to move sooner than that, nor do you want to buy when you’re advanced in your career, but in an industry which is dying or downsizing the workforce in your region (unless you have a strong Plan B).

When you get to the spot in your career where you can realistically project a stable income 7 to 10 years out, life might be giving you a green light to move forward on your homebuying dreams.

You can reasonably predict the home you’ll need in the years to come.  Since successful homeownership requires that you be ready to be in the place for a good number of years, best practice is not just to buy a home with the space and number of rooms you need right now – rather, you should aim to buy the home you’ll need 5, 7 or even 10 years down the road (to the best of your ability to predict, of course). You might be a newlywed with no kids now, but you plan to have them in a few years. Or maybe you’re a newly minted empty nester right now, but can project that you’ll want to retire – and might not want to climb two flights of stairs to get to and from your bedroom – 10 years down the road. Before you buy, you should be in a position to buy the home that meets your future needs – not just your current ones; and that requires that you have a reasonable idea of your life vision and plan for the future.

If you’re able to predict – and afford, at today’s prices – a home with the space, amenity and geographic location you’ll need 7 to 10 years from now, you might be in a good phase of life to get off the rent vs. buy fence.

With that said. . . buying a home is a massive decision and includes multiple, long-term financial and lifestyle obligations, so if one or more of these signals are present for you, that doesn’t mean you have the green light to run out and buy a home tomorrow – rather, it’s a good sign you should begin down that path, if you’re so inclined. You’ll still need to do the work to make sure your personal finances and holistic life picture are also in alignment before you buy, as well of the work it takes to ensure that your real estate and mortgage decisions are sustainable and smart, over the long-term.

It’s not overkill to check in with a mortgage pro, a tax pro, a local real estate broker or agent and a financial planner to make sure all your ducks – not just one – are in a row before you make your move.

This article was written originally published on Trulia by Tara-Nicholle Nelson.

Spring has sprung in St. Charles and St. Louis!  This is the time of year for buying and selling real estate.  There are large numbers of homes at below-market prices & the move-up market has been energized for the Spring.  Interest rates are hovering around 5% & home sale numbers have been increasing every month, it is a great time to list your home also.  Contact me for details today!
Filed Under: Buy vs. Rent, Buying a Home, Renting

  • « Previous Page
  • 1
  • …
  • 37
  • 38
  • 39
  • 40
  • 41
  • 42
  • Next Page »

Contact Sandra

Cell: 314-691-1320
Office: 636-946-2020
Contact Sandra


ReeceNichols – St. Charles

2171 Bluestone Dr.
St. Charles, MO 63303

Follow Sandra

  • Facebook
  • LinkedIn
  • Twitter
  • YouTube

Habitat for Humanity St Charles County Donations


Copyright © 2026 · Sandra Meranda · This website was Changescaped.

Copyright © 2026 · Executive Pro Theme on Genesis Framework · WordPress · Log in